
Annual Enrollment for Medicare runs October 15 – December 7, 2026. Here's what to know about comparing plans, key dates, and how to get ready.

2027 ACA Marketplace open enrollment dates continue to change. See the latest HealthCare.gov dates, key enrollment deadlines and what to know about state exchanges.
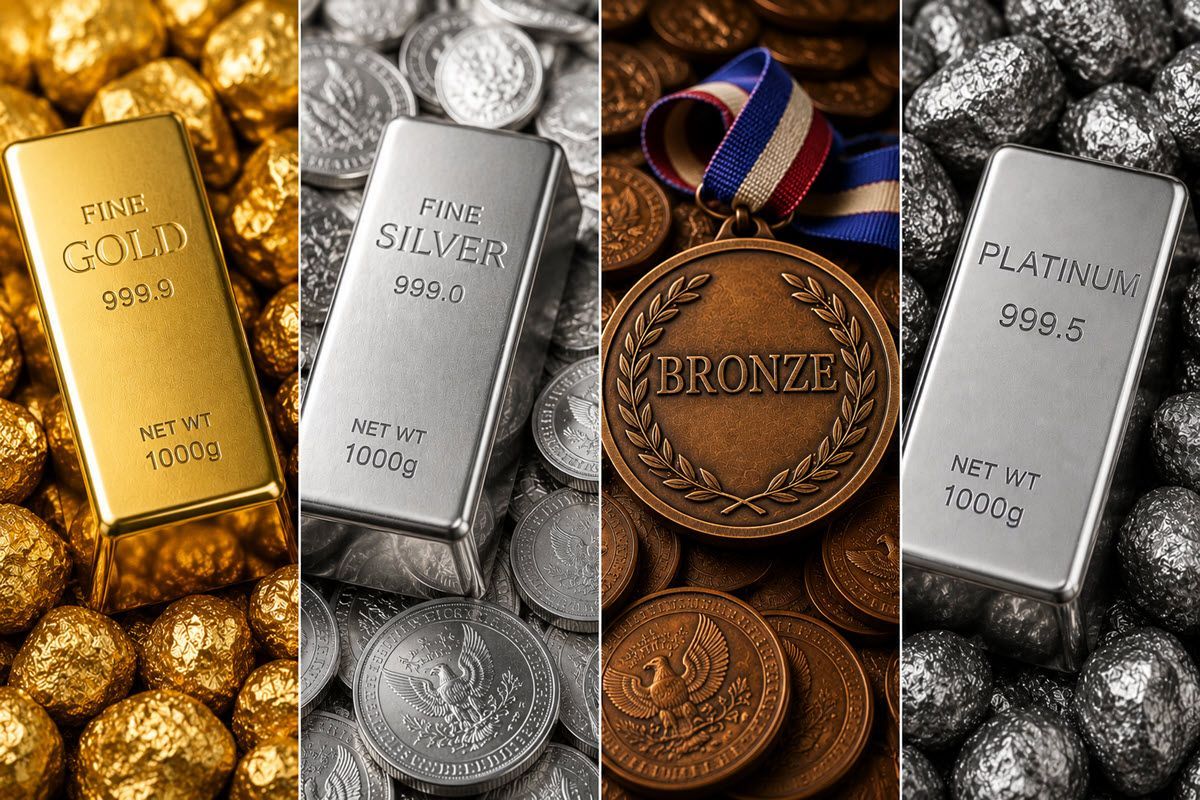
A clear guide to Health Insurance Marketplace metal tiers. Learn how Bronze, Silver, Gold, and Platinum plans split costs and how to pick the right one.
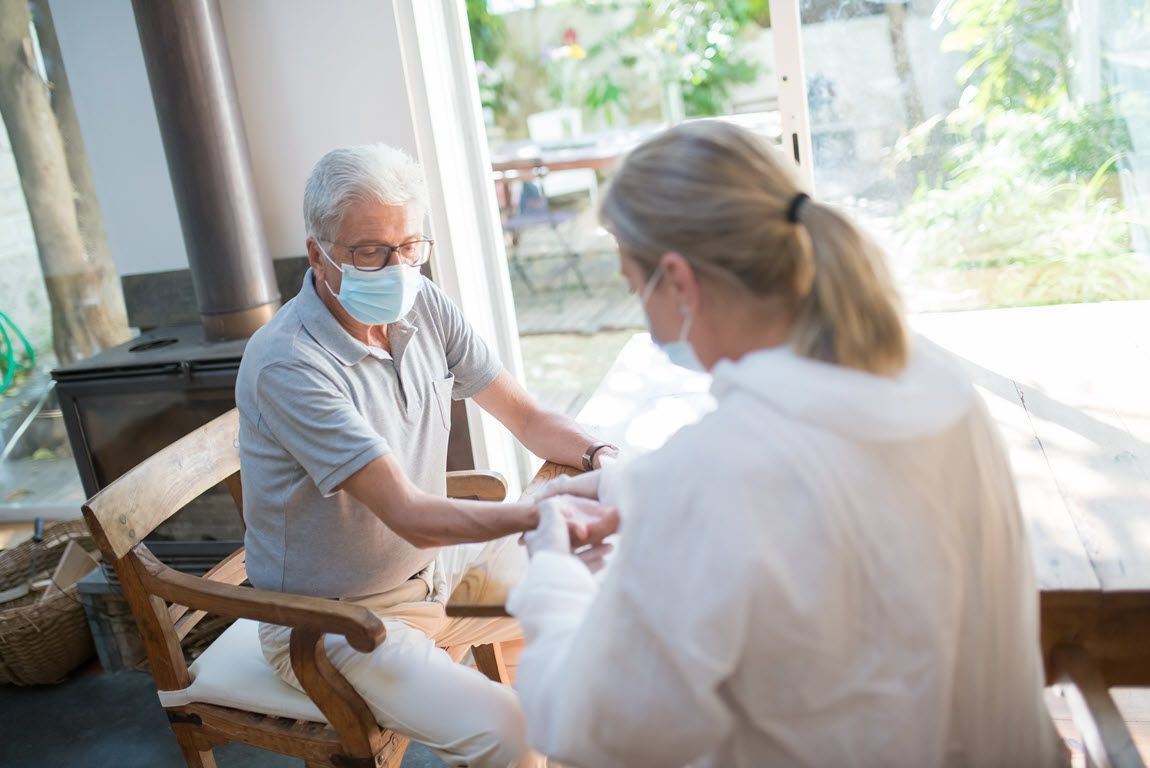
A Chronic Condition Special Needs Plan (C-SNP) is a Medicare Advantage plan built around conditions like diabetes or heart failure. See how it works.
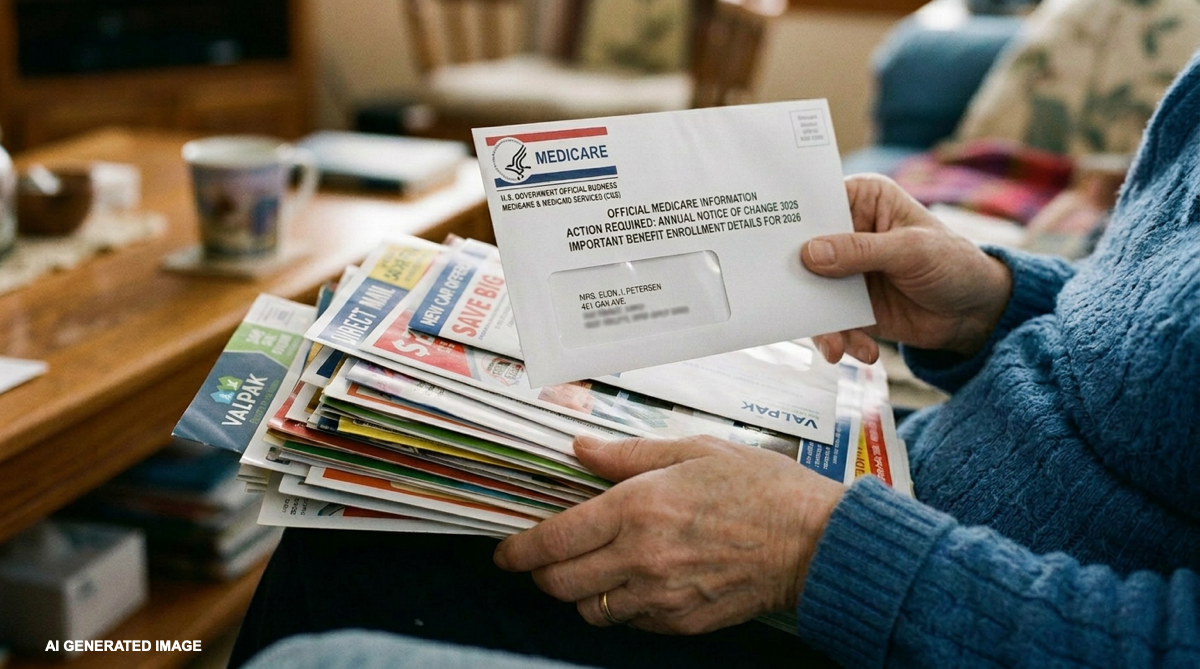
Every fall, Medicare Advantage and Part D plans mail an Annual Notice of Change. Learn what it means for your costs, coverage, and doctors next year.
Buying insurance online is fast, but a licensed agent can help you compare carriers, understand the fine print, and advocate for you at claim time.
As the summer sun beckons and thirst levels rise, it's tempting to reach for a cold, fizzy beverage. But before you pop open that soda can, consider this: your drink choice has long-term implications for your health. The Hidden Risks in Your Glass A comprehensive study by the International Agency for Research on Cancer (IARC) analyzed data from over 451,000 individuals across 10 European countries over a 16-year period. The findings revealed that consuming two or more 250 ml glasses of soft drinks daily—whether sugar-sweetened or artificially sweetened—was associated with a higher risk of all-cause mortality compared to those who drank less than one glass per month. Delving deeper: Artificially Sweetened Beverages : Individuals consuming two or more glasses daily had a 26% higher risk of death compared to those who consumed less than one glass per month. Specifically, there was a 52% increased risk of death from circulatory diseases. Sugar-Sweetened Beverages : Those consuming one or more glasses daily faced a 59% higher risk of death from digestive diseases. All Soft Drinks : A notable association was found between soft drink consumption and increased mortality from Parkinson's disease. Alternatives That Aren’t Any Healthier Think fruit juice or energy drinks are a safer bet? A study involving 13,440 U.S. adults aged 45 and older found that each additional 12-ounce serving of sugary beverages, including 100% fruit juice, was linked to an 11% higher risk of all-cause mortality. Specifically, each additional 12-ounce serving of fruit juice was associated with a 24% increased risk. Watch the sugar content of iced coffee beverages and alcoholic cocktails as well. Lifestyle Factors Matter, Too It's essential to note that high soft drink consumption often correlates with other unhealthy lifestyle choices. The IARC study observed that individuals who drank more soft drinks typically had higher body mass indexes and were more likely to smoke. Even after adjusting for factors like diet, physical activity, smoking, and education, the association between soft drink consumption and increased mortality risk remained significant. Refreshing Alternatives for the Season Looking to quench your thirst without compromising your health? Here are some delightful, healthier options: Infused Water : Add slices of citrus fruits, cucumbers, or berries to your water for a refreshing twist. Herbal Iced Teas : Brew teas like hibiscus or mint, chill them, and enjoy over ice. Sparkling Water with a Splash : Mix sparkling water with a splash of 100% fruit juice for a fizzy treat. Homemade Lemonade : Use fresh lemons, water, and a touch of natural sweetener like honey or stevia. Coconut Water : A natural source of electrolytes, perfect for rehydration. Final Thoughts Summer is a time for relaxation and enjoyment. By making informed beverage choices, you can savor the season while prioritizing your health. So, the next time you're reaching for a drink to beat the heat, consider these healthier alternatives. Your body will thank you!
Whether you’re planning a weekend getaway or a long-awaited international adventure, setting off on a trip is always exciting—but can also be unpredictable. That’s why preparing for the unexpected, especially when it comes to your health, is essential. Knowing what your medical coverage includes (and doesn’t) while traveling can help you stay healthy, avoid costly surprises, and soak up the unforgettable moments on your journey. Let’s walk through some proactive steps you can take before packing your bags—from vaccinations and insurance to emergency planning and fraud protection. 1. Know What Your Health Plan Covers—And Where Medical surprises aren’t on anyone’s itinerary—but it’s best to be prepared. Start by knowing how your insurance policy covers (or doesn’t) the region you’re traveling to. Individual health policyholders, review your insurer’s network coverage. Some plans only cover in-network or state-specific services, while others offer broader emergency coverage or travel-specific riders. Consult your insurance agent to get help reviewing your policy. Medicare beneficiaries, Original Medicare (Parts A & B) typically doesn’t cover medical care outside the U.S., except in limited circumstances. If you have a Medicare Advantage Plan, it may include emergency and urgent coverage abroad, but this varies by provider. Check your plan’s Evidence of Coverage or speak to your plan representative before traveling. 2. Consider Supplemental Insurance If you're a frequent traveler or heading abroad, look into some options to help cover you. Some options include: Travel Medical Insurance : Plans offer emergency coverage during trips outside the U.S. and tend to be affordable. Evacuation Insurance : This covers transport to a qualified medical facility if the nearest care is inadequate. An evacuation clause is often, but not always, included in a travel insurance plan. Medicare Supplement Insurance (Medigap) : Some Medigap policies cover emergency care abroad, typically up to plan limits and with a deductible. Critical Illness Insurance : A lump-sum payout can provide financial flexibility in case you’re diagnosed with a covered condition like a heart attack or stroke during travel. Be sure to read the fine print—some policies require you to be under a certain age, and preexisting conditions may not be covered. Your licensed insurance agent can help talk you through your options. 3. Keep Your Medical Info Handy Consider using a secure health app or digital wallet to access all your health records quickly. But just in case your phone is inaccessible, bring physical copies of these important documents as well: Your insurance or Medicare cards Emergency contact numbers (include the country code +1 if you’re traveling abroad) A medication list with dosages Allergy and medical condition alerts Pack all essential paperwork together in a waterproof sleeve in your luggage, and leave a second copy with someone back home. 4. Schedule Preventive Care Before Departure Most insurance plans cover preventive care services like wellness visits, vaccinations, and screenings. Before your trip, check these tasks off your list: Get vaccinated : Make sure you’re up to date on your flu, COVID-19, and tetanus shots. If traveling internationally, check the CDC recommendations for the region you’re visiting, which may include Hepatitis A/B, typhoid, or yellow fever vaccinations.
Imagine getting a call in the middle of the night from someone claiming to be your grandchild, panicked and in trouble. They say they’ve been in an accident or arrested—and they desperately need money. Your heart races. You’d do anything to help. That’s exactly what scammers are counting on. The Federal Communications Commission (FCC) has recently issued a warning about a rise in what's known as the “grandparent scam” —a sneaky and heartless scheme targeting older adults with urgent, emotional phone calls meant to trick them into sending money. What Is the Grandparent Scam? These scams usually start with a phone call from someone pretending to be your grandchild (or another close relative). They’ll say they’re in trouble—maybe stuck in jail or in a hospital—and they need money fast for bail, legal fees, or emergency expenses. To make things even more convincing, they may hand the phone off to someone pretending to be a lawyer or a police officer. And they’ll likely ask you not to tell anyone—saying it’s a “private” or “sensitive” situation. That sense of urgency is key to the scam. It’s meant to bypass your instinct to double-check and make you act fast—before you have time to think it through or talk to someone else. Why It Works—and Why It’s Dangerous These calls often come late at night or early in the morning, when you’re more likely to be caught off guard. The scammer might not even say who they are—just “Grandma, it’s me”—and hope you fill in the blank for them. From there, they use that information to sound more convincing. Some victims have been asked to send money via wire transfer, cryptocurrency, gift cards, or even in cash via courier—all methods that are difficult or impossible to trace or reverse. According to the FCC, scammers using this method have stolen tens of millions of dollars from seniors across the U.S. Watch for These Warning Signs If you or someone you love receives a call like this, here are some red flags that it could be a scam: High pressure and urgency – You’re told to act immediately Vague or strange details – They may not identify themselves clearly, or hope you’ll say the grandchild’s name for them Unverifiable location or story – They say they’re in jail overseas or in a place where you can’t easily check on them Unusual payment requests – Gift cards, Bitcoin, wire transfers, or cash deliveries Calls at odd hours – Scammers try to catch you when you’re less alert What To Do If You Get a Suspicious Call If something doesn’t feel right, trust your gut. Here’s what you can do to stay safe: ✅ Hang up and verify – Call your grandchild or their parent using a phone number you know is theirs ✅ Talk to someone you trust – A second opinion from a friend or family member can make all the difference ✅ Don’t rely on caller ID – Scammers often “spoof” numbers to make it look like someone you know is calling ✅ Block the number – Use your phone’s settings to block suspicious calls ✅ Report the scam – Contact the National Elder Fraud Hotline at 833-FRAUD-11 and file a complaint with the FCC What If You’ve Already Sent Money? First of all, don’t panic—and know that you’re not alone. Scammers are incredibly convincing, and even smart, cautious people have been tricked. Here’s what to do: Call your bank or payment service right away – They may be able to stop or reverse the transaction if it's recent Report it – Contact the FCC, your local police, and the FBI’s Internet Crime Complaint Center at ic3.gov Let your family know – They can help protect you and others from future attempts Help Protect Others, Too The more people know about this scam, the harder it becomes for criminals to succeed. Please share this information with friends, neighbors, and especially your older loved ones. A quick conversation now could prevent a heartache later. And remember—if you ever get a call like this and aren’t sure what to do, don’t rush. Take a breath, hang up, and check in with someone you trust. Real family emergencies don’t come with secret demands or payments via gift cards.